How Agentic AI Is Transforming Banking Operations: And What Fintech Leaders Need to Do Right Now

How Agentic AI Is Transforming Banking Operations: And What Fintech Leaders Need to Do Right Now
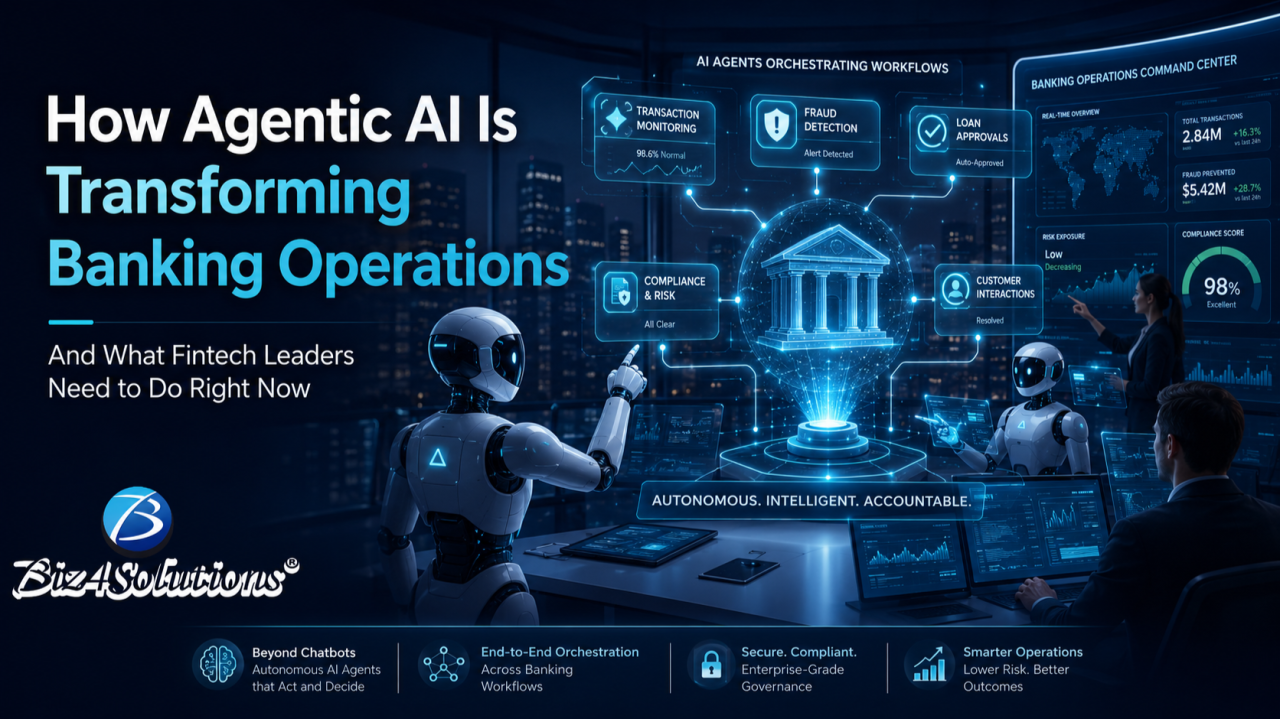
There is a moment in every technology cycle when the question shifts from “should we explore this?” to “why haven’t we started yet?” For agentic AI in banking, that moment has arrived.

The chatbot era gave banking customers a way to ask questions and get scripted answers. It was progress, but it was also a ceiling. The real transformation happening right now is not about better chatbots or smarter FAQ responses. It is about AI systems that can perceive a situation, make a decision, execute an action, and adapt when something changes – all without waiting for a human to approve every step.

That is what agentic AI means. And the gap between institutions that understand this and those still thinking in terms of “automation” is widening fast.

The Numbers That Should Be on Every CTO’s Radar

According to a report by Marketsand Markets, “the global agentic AI market stood at $5.1 billion in 2024 and is projected to surpass $47 billion by 2030, representing a compound annual growth rate of over 44.8%”.

For fintech founders and IT decision-makers still treating this as a watch-and-wait situation, these figures represent the cost of delay, not just the size of an opportunity.

What Makes Agentic AI Different from Everything That Came Before

Most banking AI to date has been reactive and single-purpose. A fraud detection model flags an anomaly. A chatbot answers a question. A credit scoring algorithm produces a number. Each of these systems does one thing in isolation, then hands off to a human.

Agentic AI changes the architecture entirely. An agent does not just flag the anomaly; it investigates it, cross-references it against account history and behavioral patterns, decides whether to block or allow the transaction, communicates with the customer if needed, and logs the entire decision trail for compliance purposes. It does this in milliseconds, across millions of transactions simultaneously, and it learns from each cycle.

The difference is not incremental. It is structural.

Think of it this way: previous AI was a tool that made humans faster. Agentic AI is a system that handles entire workflows independently, escalating to humans only when the situation genuinely requires judgment that the system cannot confidently provide.

Where Agentic AI Is Already Delivering in Banking Operations

Fraud Detection and Financial Crime Prevention

More than half of banking executives report high capability in fraud detection (56%) and security (51%) as the leading use cases for agentic AI, with banks using AI agents to continuously monitor suspicious activities and automatically respond to threats.

This is not just an efficiency gain, it is a fundamental shift in how financial crime is fought. Agents operating at transaction speed, with full context, make decisions that no human analyst could make at that volume or velocity.

Loan Origination and Credit Processing

Leading regional banks implementing agentic AI report noteworthy improvement in approval-to-funding cycles for commercial lending and a reduction in manual processing for trade finance operations.

Loan origination is one of the most document-heavy, decision-intensive processes in banking. Agents that can ingest application data, pull bureau reports, assess risk, flag exceptions, generate term sheets, and route for final sign-off represent a step-change in operational throughput, without any reduction in underwriting quality.

Compliance and Regulatory Reporting

Compliance is the area where the cost of manual labor is most visible and most painful. Regulatory requirements demand exhaustive documentation, real-time monitoring, and continuous reporting across multiple jurisdictions. An agentic system can monitor transactions against evolving rule sets, generate Suspicious Activity Reports automatically, maintain audit trails without human intervention, and adapt its behavior when regulations change.

Customer Lifecycle Management

The shift from reactive customer service to proactive lifecycle management is one of the most commercially significant applications of agentic AI. Rather than waiting for a customer to call or a churn signal to appear on a dashboard, agents can monitor behavioral indicators, identify the right intervention moment, personalize an offer, deliver it through the right channel at the right time, and capture the response; all within a single automated loop.

Banks deploying agentic AI report 35-55% faster resolution times for complex customer queries. For fintech businesses where speed and personalization are core to the value proposition, this is not a marginal improvement; it is table stakes.

The Architecture Behind Agentic Banking Systems

Understanding what makes agentic AI work in a banking context matters for CTOs and IT leaders evaluating build vs. buy decisions and integration strategies.

At the core, an agentic banking system requires four components working together.

1. The first is a reasoning layer, typically a large language model or a fine-tuned variant, that can interpret unstructured inputs (documents, conversations, transaction narratives), apply business logic, and produce structured decisions.

2. The second is a tool-use layer: the set of APIs, databases, and systems the agent can call. This is where integration depth matters most. An agent that cannot write back to the core banking system, update CRM records, or trigger downstream workflows is not truly agentic; it is still a glorified classifier.

3. The third is a memory layer: the ability to retain context across interactions, sessions, and time. This is what separates agents that learn from agents that simply repeat. Vector databases and persistent state management are the technical mechanisms behind this.

4. The fourth is a governance layer: the guardrails, audit logs, human escalation triggers, and compliance controls that make agentic systems safe to deploy in regulated environments. This layer is not optional. It is what determines whether a deployment survives its first regulatory examination.

The Honest Challenges – Because the Hype Leaves Them Out

Not everything about agentic AI in banking is smooth. The technology is mature enough to deploy, but not yet mature enough to deploy carelessly.

The primary friction points are integration complexity, data quality, and governance readiness. Core banking systems were not designed with agent interoperability in mind. Data silos persist across most institutions. And compliance teams, rightly, want to understand exactly how an autonomous system makes decisions before they sign off on it operating at scale.

The institutions winning with agentic AI are not the ones deploying maximum autonomy. They are the ones deploying precisely calibrated autonomy, with clear human oversight at the right decision points.

The practical approach: start with a contained, high-value process, prove the ROI, build organizational confidence, then scale. This is what separates successful deployments from expensive pilots that never graduate.

What This Means for Fintech Founders and Technology Leaders Specifically

Fintech companies occupy a particular position in this landscape. Unlike incumbents, you are not carrying the weight of a 40-year-old core banking system. Your data architecture is newer. Your teams are more comfortable with AI tooling. Your regulatory footprint, while real, is more navigable.

This means the gap between where you are and where agentic AI can take you is smaller, and the competitive advantage available to you is proportionally larger.

The strategic questions worth asking now are practical ones.

·  Which of your current operational workflows involve the most repetitive decision-making against structured rules?

·   Where does human bottlenecking create latency in customer-facing processes?

·   Which compliance functions are consuming disproportionate headcount?

·   Where is your false positive rate in fraud detection high enough to be costing you customer relationships?

These are the entry points. Not an enterprise transformation program. Not a three-year roadmap. Specific workflows, specific friction points, specific agents deployed against specific problems, and then expanded as the results justify the investment.

The Window Is Open, But Not Indefinitely

In late 2025, just over a quarter of banks had AI agents in production for cloud operations. By the end of 2026, adoption is expected to surge beyond 70%. The institutions making deployment decisions today are positioning themselves ahead of that wave. Those waiting for the technology to mature further are likely waiting past the optimal window.

The chatbot era taught banks that digital engagement matters. The agentic AI era is teaching them that autonomous, intelligent operations are the actual competitive moat; and it is being built right now, by the organizations willing to move with appropriate urgency.

The question for fintech founders and IT decision-makers is not whether agentic AI will reshape banking operations. It already is. The question is whether your organization is shaping that change or reacting to it.

Biz4Solutions is a software development agency specializing in AI-powered platforms, SaaS systems, and intelligent automation for fintech and financial services organizations. If you are evaluating how to build agentic AI capabilities into your banking or fintech operations, we would be glad to discuss the technical approach and share relevant experience.
 

How Can AI Help US Real Estate Providers Shorten the Sales Cycle from 90 Days to 30 Days?

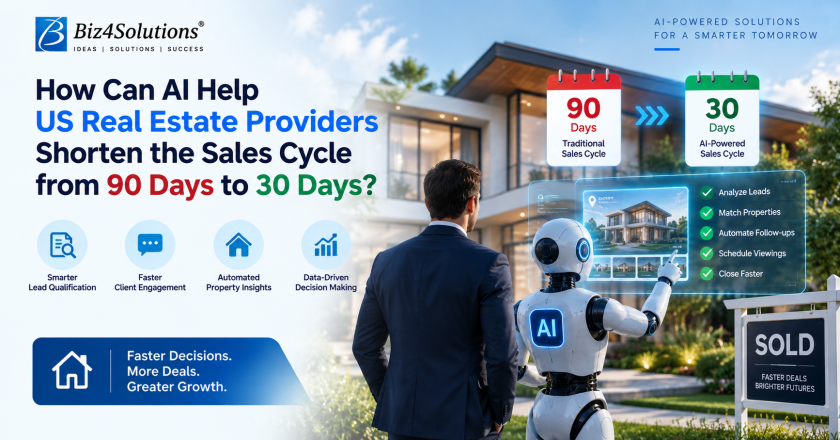
How Can AI Help US Real Estate Providers Shorten the Sales Cycle from 90 Days to 30 Days?

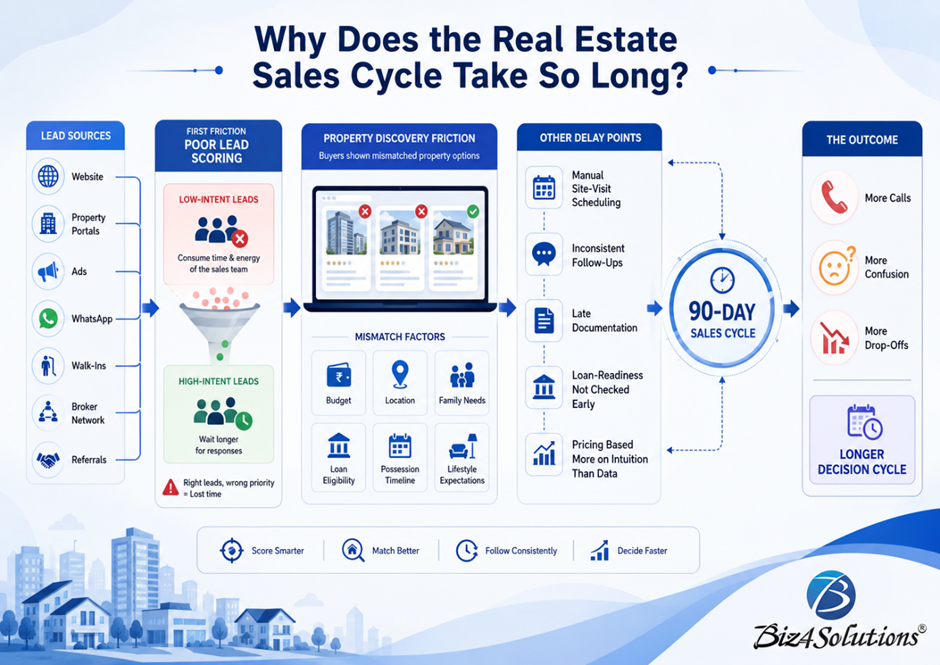
For many real estate providers, the problem is not just getting more leads. The harder problem is identifying which buyers are serious, responding before interest fades, matching them with the right listings, coordinating showings quickly, and moving them toward mortgage-readiness and closing without unnecessary friction.

A long real estate sales cycle is rarely caused by one single delay. It usually happens because small gaps keep adding up across the buyer journey.

· A lead waits too long for a response.

· A buyer receives listings that do not match their budget, lifestyle, school district preference, commute expectations, or move-in timeline.

· A showing is not scheduled fast enough.

·  Follow-ups become generic.

·  Mortgage pre-approval is discussed too late.

·  Transaction steps such as disclosures, inspection, appraisal, title, escrow, and documentation remain scattered across different systems.

This is exactly where AI in real estate can make a practical difference. Not by replacing agents, brokers, leasing teams, or sales representatives, but by helping them work faster, prioritize better, and personalize the buyer journey at scale.

Why Are US Real Estate Sales Cycles Still So Slow?

The US real estate market is already highly digital, but many sales operations are still fragmented. Buyers may come from brokerage websites, IDX search pages, Zillow, Realtor.com, Redfin, Google Ads, Facebook and Instagram campaigns, open houses, model home visits, agent referrals, phone calls, SMS inquiries, and CRM landing pages. But once the lead enters the system, many real estate teams still rely on manual qualification, inconsistent follow-ups, disconnected spreadsheets, and basic CRM notes.

According to the National Association of REALTORS®, buyers spent a median of 10 weeks searching for a home in 2025, and 52% found their home through an online search. That means the digital discovery phase is already central to the US home-buying journey, but the sales workflow behind that discovery often remains slow, reactive, and heavily dependent on manual coordination.

For real estate brokerages, agent teams, home builders, leasing companies, property managers, and PropTech platforms, the real challenge is no longer just online visibility. The bigger challenge is converting digital interest into qualified conversations, scheduled showings, serious offers, and completed transactions faster.

Can AI Really Reduce a 90-Day Sales Cycle to 30 Days?

With AI usage, the sales cycle can be minimized, if it’s used to remove delay points throughout the journey. It cannot force a buyer to make a decision, and it cannot eliminate market realities such as mortgage rates, appraisal timelines, inspection issues, or title dependencies. But it can compress the time wasted before a serious buyer reaches the right property, the right agent, and the right next step.

For example, an AI-powered real estate CRM can analyze lead behavior across multiple touchpoints. A consumer who repeatedly views the same listing, saves homes in a specific neighborhood, checks mortgage estimates, opens emails, and requests school district information shows strong buying intent. They should not be treated the same as someone who casually filled out a form just once. AI lead scoring helps sales teams separate high-intent buyers from low-intent traffic. This allows agents and inside sales teams to prioritize the prospects most likely to move forward in the near term. Instead of spending days chasing cold leads, teams can focus on buyers who are showing real purchase signals.

How Does AI Improve Lead Qualification for Real Estate Providers?

Lead qualification is one of the biggest bottlenecks in real estate sales. Many teams receive leads from different platforms, but they do not always know which source is producing serious buyers, which inquiries need immediate follow-up, and which prospects are still early in the research stage.

AI can evaluate buyer intent using data points such as search activity, budget range, preferred ZIP codes, saved listings, requested showings, mortgage pre-approval status, engagement history, communication response time, and property comparison behavior.

For a brokerage, this means agents can receive a ranked list of leads instead of a flat contact list. For a home builder, this means sales teams can identify which buyers are ready for a model home tour. For a leasing company, this means the team can prioritize renters who are ready to move within a defined lease-start window. For a PropTech platform, this means better conversion analytics and more intelligent buyer routing.

The result is simple: the right lead reaches the right person faster.

Why Do Buyers Drop Off During Property Discovery?

Many buyers do not drop off because they are uninterested. They drop off because the process becomes confusing. They are shown too many homes, the wrong homes, or listings that do not match their actual decision criteria.

Homebuyers often consider far more than just price or square footage. Factors like commute convenience, school districts, HOA costs, property taxes, insurance expenses, neighborhood walkability and safety, resale opportunities, rental income potential, pet regulations, nearby medical facilities, and the home’s readiness for immediate move-in can all influence their decision.

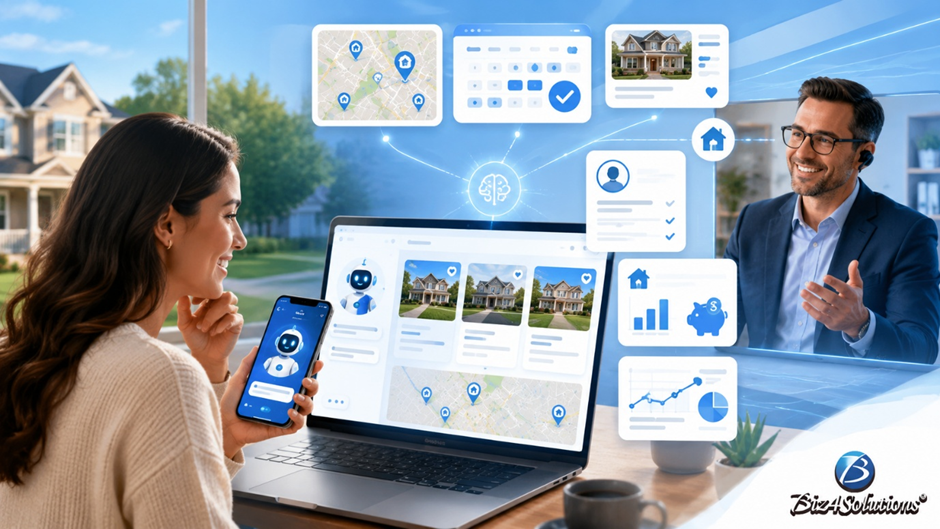
A custom AI property recommendation engine can go beyond standard search filters. It can understand buyer preferences and recommend homes based on a richer decision profile. Instead of showing 40 listings that technically match a ZIP code and price range, the system can recommend 5 to 7 better-fit options based on lifestyle, financing readiness, urgency, and previous interactions.

This is where custom real estate software development becomes powerful. A generic property search experience can show listings. A custom AI-powered real estate platform can guide buyers toward better decisions.

How Can AI Speed Up Buyer Conversations Without Making Them Feel Robotic?

Real estate in the US is still built on confidence, timing, and human trust. Buyers expect fast answers, but they also want to feel understood. When a chatbot gives canned replies, it can make the experience feel impersonal. But when an AI assistant is designed around real buyer intent, property data, and sales context, it can support the conversation in a much more natural way.

For example, a buyer may be looking for a three-bedroom home within a specific budget, close to downtown Austin, in a pre For home builders, ferred school district, and available within a short move-in window. A basic chatbot may only respond with a broad list of homes or ask the buyer to wait for an agent. A smarter AI sales assistant can interpret the request, check available listings, consider location and budget constraints, compare matching homes, estimate likely monthly payments, and suggest the next practical step, such as scheduling a showing.

For US real estate providers, the real value comes when the AI assistant is not working in isolation. It should connect with IDX or MLS listing feeds, CRM data, current inventory, showing calendars, SMS and email workflows, mortgage partner processes, and previous buyer interactions. When these systems work together, AI becomes more than a front-end chatbot. It becomes a connected sales support layer that helps agents respond faster while keeping the experience personal.

What Happens After the Showing?

Many real estate opportunities lose momentum after the first showing. The buyer may be interested, but the next step is not always clear. The agent may not have a complete record of what the buyer liked, what concerns came up, or which competing properties the buyer is still considering. In the case of home builders, the buyer may also be waiting for floor plan comparisons, financing options, incentive details, or availability updates.

AI can help organize this post-showing stage. It can summarize the buyer’s feedback, capture objections, identify likely concerns, and suggest a follow-up action for the agent. If the buyer is worried about affordability, the system can recommend sending mortgage payment estimates. If the buyer likes the neighborhood but hesitates on price, the platform can prepare comparable property information or recent market data. If the buyer asks about schools, commute time, or HOA fees, the system can help the agent respond with relevant information quickly.

This does not reduce the importance of the agent. It gives the agent better context, faster access to information, and a clearer path for the next conversation.

Can AI Help with Mortgage-Readiness and Closing Coordination?

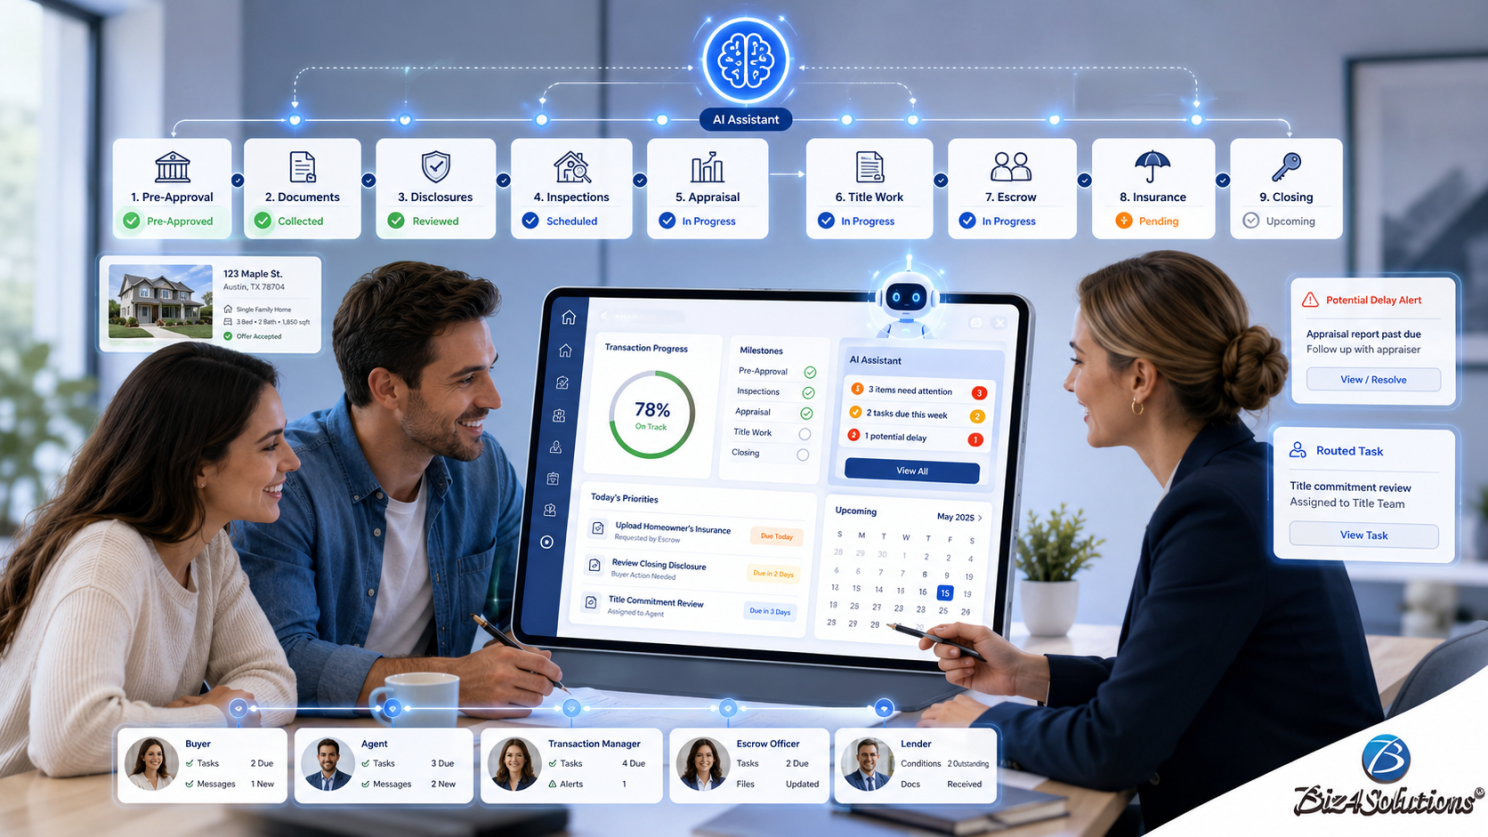
Yes. In the US market, deals often slow down because key steps are spread across different people, systems, and timelines. Mortgage pre-approval, document collection, disclosures, inspections, appraisals, title work, escrow coordination, insurance requirements, and closing tasks may all move through separate workflows.

An AI-enabled real estate platform can help bring visibility into this process. It can show buyers what is still pending, remind them about missing documents, route tasks to the right team, summarize transaction progress, and flag delays before they put the deal at risk. For brokerages, this improves transaction visibility. For home builders, it helps sales, financing, and operations teams stay aligned without repeated manual coordination. For PropTech companies, it creates a smoother experience from search to closing.

The point is not just to add AI as another feature. The bigger opportunity is to redesign the sales and transaction workflow so that buyers, agents, managers, and support teams can act on the same information at the right time.

What Could a 30-Day AI-Enabled Real Estate Sales Journey Look Like?

A buyer may first enter through a brokerage website, listing portal, paid campaign, open house form, or referral. Instead of being added to a generic contact list, the AI system can immediately assess buyer intent based on activity, preferences, urgency, and engagement signals.

The buyer can then interact with an AI assistant that understands budget, preferred location, home type, financing readiness, commute needs, school preferences, and move-in timeline. Instead of overwhelming the buyer with too many unsuitable listings, the platform can present a focused set of relevant homes.

From there, the buyer can schedule a showing directly through the system. After the showing, the platform can generate a personalized follow-up, highlight buyer objections, and recommend the next action for the agent. Mortgage-readiness can be checked earlier, documents and disclosures can be tracked digitally, and sales managers can see which buyers are progressing and which ones are stuck.

In this type of workflow, AI does not replace the relationship between buyer and agent. It removes the delays around that relationship.

What Should Real Estate Providers Ask Before Building an AI Platform?

Before investing in AI software development, real estate leaders should first identify the areas that are slowing down the sales cycle. Is the first response taking too long? Are agents spending too much time on low-intent leads? Are buyers receiving listings that do not match their actual needs? Are showings still scheduled manually? Are follow-ups inconsistent? Is mortgage-readiness checked too late? Are transaction updates scattered across too many tools?

These questions matter because AI should solve a real operational problem. A chatbot alone will not shorten the sales cycle. A connected AI sales platform can make a much stronger impact when it improves lead prioritization, buyer communication, showing coordination, follow-up quality, and transaction visibility.

What Features Should a US-Focused AI Real Estate Platform Include?

A US-focused AI real estate platform can include AI lead scoring, IDX or MLS-connected property search, intelligent listing recommendations, AI-assisted buyer conversations, showing scheduling, CRM integration, SMS and email automation, personalized follow-up workflows, mortgage-readiness tracking, buyer journey analytics, agent dashboards, broker dashboards, open house lead capture, transaction task tracking, document workflows, e-signature integration, and sales reporting.

For PropTech startups and SaaS products, the platform may also need multi-tenant architecture, role-based access, subscription billing, API integrations, security controls, mobile apps for buyers and agents, and analytics dashboards for business performance.

The better approach is not to build every feature at once. Start with the area that creates the most delay, prove the business value, and then expand the platform in phases.

Why Build Custom AI Software Instead of Using Generic Real Estate Tools?

Generic real estate tools can support basic CRM, email automation, or listing search. But every real estate business has its own sales process, market focus, customer segments, team structure, listing strategy, compliance needs, integrations, and reporting requirements.

A brokerage may need AI lead routing and agent productivity dashboards. A home builder may need model home scheduling, inventory visibility, and buyer financing workflows. A property management company may need leasing automation and renter qualification. A PropTech startup may need a custom SaaS platform with AI-powered search, recommendations, and buyer engagement.

Custom AI software allows these workflows to be designed around the business model, not forced into a generic template.

Final Thoughts: AI Will Not Replace Real Estate Sales Teams, But It Will Redesign How They Sell

The real estate sales cycle becomes long when serious buyers are not identified early, property discovery is not personalized, follow-ups are inconsistent, showing coordination is manual, and transaction readiness is handled too late.

AI can help real estate providers reduce these delays by connecting lead intelligence, property recommendations, buyer communication, showing workflows, mortgage-readiness, and transaction visibility into one smarter system.

For brokerages, home builders, leasing companies, property managers, and PropTech startups, the opportunity is not just to use AI. The opportunity is to build a sales engine where every buyer interaction moves the deal one step closer to a decision.

A shorter sales cycle is not only a sales goal. It is a software design opportunity.